Did you know that homeowner’s insurance doesn’t cover flood damage? Because of this, homes located in a Special Flood Hazard Area (SFHA) are required by lenders to purchase a separate flood insurance policy. However, there are millions of homes at risk that also experience periodic flooding but are not located in the most hazardous zones.
Regardless, any homeowner can purchase flood insurance and the good news is that, for some, rates will be reduced this year.
Starting on Oct. 1, the National Flood Insurance Program (NFIP) launched a new program called Risk Rating 2.0. This program is designed to encourage communities throughout the country to deploy measures that help mitigate potential damage due to flooding. The lower the risk resulting from these efforts, the higher the rating. This means that many homeowners who live in highly rated areas may benefit from lower premiums going forward. However, be aware that there is only one source of insurance sponsored by the government, rates are standardized and payouts are capped at $250,000.
But not to worry, flood insurance also is available in the private market. Private insurers are able to customize premium quotes and the forces of competition help keep premiums reasonable, so it’s a good idea to comparison shop. Private flood insurance policies also offer additional coverage options that the NFIP does not, such as:
Up to $1 million or more in building coverage
Enhanced coverage for detached structures
Replacement cost for contents and secondary residences
Additional living expenses
Pool repair and fill
Business income coverage
If your home is not in a SFHA and you are wondering whether or not to purchase flood insurance, consider how much you can afford to pay out-of-pocket for flood damage. Use this statistic as a guide: 1 inch of floodwater can cause as much as $25,000 in damages to a home.
In other words, paying for flood insurance is kind of like paying a fee to protect your home equity and investment portfolio. Compare a flood policy to buying a warranty for a new appliance. The risk is that the cost of repairing or replacing that appliance would put a strain on your finances. If you apply that same logic to 1 inch of flood damage, you can see that a flood policy would offer a much higher return on the amount you invest in its premium. Since a single flood event could wipe out all of your assets, it stands to reason that insurance is critical for perils that pose high financial risks.
If you still need more data to help decide whether to buy a flood insurance policy, consider the impact that extreme weather events have had on your property in recent years. In many areas, flood damage isn’t caused by a hurricane, but rather by storm surges or heavy rainfall. Even if you haven’t experienced significant events, that could change due to the constantly evolving environment. Rising sea levels and new weather patterns are expected to produce higher intensity flooding from hurricanes and offshore storms.
One way to see the local flood patterns in your area is to visit Floodfactor.com. Navigate the Floodfactor map to pinpoint your home’s exact location, and compare patterns based on past, recent, and projected future weather events.
Flood Insurance: Insuring Your Home
November 1, 2021 · Blog, Financial Planning, News
⏱ 3 min read
Did you know that homeowner’s insurance doesn’t cover flood damage? Because of this, homes located in a Special Flood Hazard Area (SFHA) are required by lenders to purchase a separate flood insurance policy. However, there are millions of homes at risk that also experience periodic flooding but are not located in the most hazardous zones.
Regardless, any homeowner can purchase flood insurance and the good news is that, for some, rates will be reduced this year.
Starting on Oct. 1, the National Flood Insurance Program (NFIP) launched a new program called Risk Rating 2.0. This program is designed to encourage communities throughout the country to deploy measures that help mitigate potential damage due to flooding. The lower the risk resulting from these efforts, the higher the rating. This means that many homeowners who live in highly rated areas may benefit from lower premiums going forward. However, be aware that there is only one source of insurance sponsored by the government, rates are standardized and payouts are capped at $250,000.
But not to worry, flood insurance also is available in the private market. Private insurers are able to customize premium quotes and the forces of competition help keep premiums reasonable, so it’s a good idea to comparison shop. Private flood insurance policies also offer additional coverage options that the NFIP does not, such as:
Up to $1 million or more in building coverage
Enhanced coverage for detached structures
Replacement cost for contents and secondary residences
Additional living expenses
Pool repair and fill
Business income coverage
If your home is not in a SFHA and you are wondering whether or not to purchase flood insurance, consider how much you can afford to pay out-of-pocket for flood damage. Use this statistic as a guide: 1 inch of floodwater can cause as much as $25,000 in damages to a home.
In other words, paying for flood insurance is kind of like paying a fee to protect your home equity and investment portfolio. Compare a flood policy to buying a warranty for a new appliance. The risk is that the cost of repairing or replacing that appliance would put a strain on your finances. If you apply that same logic to 1 inch of flood damage, you can see that a flood policy would offer a much higher return on the amount you invest in its premium. Since a single flood event could wipe out all of your assets, it stands to reason that insurance is critical for perils that pose high financial risks.
If you still need more data to help decide whether to buy a flood insurance policy, consider the impact that extreme weather events have had on your property in recent years. In many areas, flood damage isn’t caused by a hurricane, but rather by storm surges or heavy rainfall. Even if you haven’t experienced significant events, that could change due to the constantly evolving environment. Rising sea levels and new weather patterns are expected to produce higher intensity flooding from hurricanes and offshore storms.
One way to see the local flood patterns in your area is to visit Floodfactor.com. Navigate the Floodfactor map to pinpoint your home’s exact location, and compare patterns based on past, recent, and projected future weather events.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Today, 70 percent of college students graduate with an average of $30,000 in student loan debt. The average payment is nearly $400 a month and will take about 20 years to pay off. On an individual level, paying off high debt can delay hopes of saving to buy a house, start a family, launch a business or invest for retirement.
On a broader level, the national burden of student debt could impact America’s economic future. When young adults are unable to afford home ownership, that reduces spending on all types of consumer products that accompany home buying. It also reduces property taxes used to support local resources and reduces the insurance pool of property owners used to help repair and rebuild homes after extreme weather crises.
Whether you’re a graduate or the relative of a graduate in this situation, it’s worth considering various strategies to help pay off this debt. After all, it may be better – for both your offspring and the country’s GDP – to financially help them out now rather than later via a larger inheritance.
High Interest and Consolidation Considerations
The strategic way to approach student debt is to focus on paying off high-interest loans first. This generally includes private loans and any others with variable interest rates that may increase over time. Be aware that with federal student loans, there are different types and the borrower is permitted to switch to a different payment plan that better suits his needs over time. Another option is to consolidate student loans. However, if sometime in the future federal student loans are forgiven, your student could miss out on that by transferring or consolidating to a privately held loan.
Employer Assistance Programs
In recognition of student loan debt as both a personnel and national concern, many employers are starting to offer repayment assistance programs – even to parents paying off parent student loans. It’s important to inquire whether or not an employer offers this benefit, as they are not always promoted – especially to current workers. However, these programs have become more appealing to companies since passage of the CARES Act, which extended pre-tax employer-provided educational assistance for up to $5,250 per employee, per year through 2025
Another program that some companies have introduced is the ability for employees to convert the cash value of unused paid-time-off (PTO) toward their student loan payments. In other words, if a worker is not able to use all of his accrued paid vacation days in a given year, he can request the employer contribute that income toward his student loan debt.
College Savings Plans
Each state sponsors a Section 529 college savings and investment plan, which feature tax-deferred growth and tax-free withdrawals when used to pay for qualified education expenses.
In 2019, as part of the Setting Every Community Up for Retirement Enhancement (SECURE) Act, Congress included a provision that permits up to $10,000 (a lifetime cap, per each beneficiary) from 529 College Savings Plans to be used to repay student loans. For example, if a family has three college students, the parents may withdraw up to $30,000 to help pay off that debt from their 529 account(s). Note that a 529 account owner can change the 529 plan beneficiary at any time without tax consequences.
Be aware, however, if 529 college funds are used to make principal and interest payments on a qualified student loan, that student loan interest cannot be claimed as a deduction on their tax return.
Strategies for Paying Off Student Loans
October 1, 2021 · Blog, Financial Planning, News
⏱ 3 min read
Today, 70 percent of college students graduate with an average of $30,000 in student loan debt. The average payment is nearly $400 a month and will take about 20 years to pay off. On an individual level, paying off high debt can delay hopes of saving to buy a house, start a family, launch a business or invest for retirement.
On a broader level, the national burden of student debt could impact America’s economic future. When young adults are unable to afford home ownership, that reduces spending on all types of consumer products that accompany home buying. It also reduces property taxes used to support local resources and reduces the insurance pool of property owners used to help repair and rebuild homes after extreme weather crises.
Whether you’re a graduate or the relative of a graduate in this situation, it’s worth considering various strategies to help pay off this debt. After all, it may be better – for both your offspring and the country’s GDP – to financially help them out now rather than later via a larger inheritance.
High Interest and Consolidation Considerations
The strategic way to approach student debt is to focus on paying off high-interest loans first. This generally includes private loans and any others with variable interest rates that may increase over time. Be aware that with federal student loans, there are different types and the borrower is permitted to switch to a different payment plan that better suits his needs over time. Another option is to consolidate student loans. However, if sometime in the future federal student loans are forgiven, your student could miss out on that by transferring or consolidating to a privately held loan.
Employer Assistance Programs
In recognition of student loan debt as both a personnel and national concern, many employers are starting to offer repayment assistance programs – even to parents paying off parent student loans. It’s important to inquire whether or not an employer offers this benefit, as they are not always promoted – especially to current workers. However, these programs have become more appealing to companies since passage of the CARES Act, which extended pre-tax employer-provided educational assistance for up to $5,250 per employee, per year through 2025
Another program that some companies have introduced is the ability for employees to convert the cash value of unused paid-time-off (PTO) toward their student loan payments. In other words, if a worker is not able to use all of his accrued paid vacation days in a given year, he can request the employer contribute that income toward his student loan debt.
College Savings Plans
Each state sponsors a Section 529 college savings and investment plan, which feature tax-deferred growth and tax-free withdrawals when used to pay for qualified education expenses.
In 2019, as part of the Setting Every Community Up for Retirement Enhancement (SECURE) Act, Congress included a provision that permits up to $10,000 (a lifetime cap, per each beneficiary) from 529 College Savings Plans to be used to repay student loans. For example, if a family has three college students, the parents may withdraw up to $30,000 to help pay off that debt from their 529 account(s). Note that a 529 account owner can change the 529 plan beneficiary at any time without tax consequences.
Be aware, however, if 529 college funds are used to make principal and interest payments on a qualified student loan, that student loan interest cannot be claimed as a deduction on their tax return.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
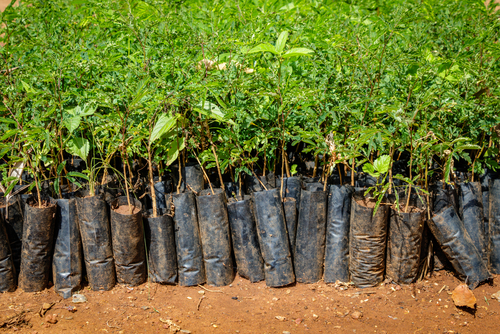
President Biden re-entered the United States in the Paris Agreement. This is an international treaty first signed in 2015 in which countries around the globe committed to mitigating climate change. Specifically, the goal of the Paris Accord is to limit global warming to no more than 1.5 degrees Celsius above pre-industrial levels.
This objective would generate what is called a net zero global economy, which means creating a balance between the amount of greenhouse gases produced and the amount of greenhouse gasses removed from the atmosphere. The main engine that places carbon back into the soil is healthy vegetation that grows all years round, these are called cover crops and reforestation. You can help by using the Ecosia search engine.
The initial benchmark is to achieve net zero carbon dioxide emissions by 2050 and net zero emissions of all greenhouse gases by 2070. However, accomplishing these lofty goals will require a remarkable transformation of the global economy and global farming practices.
A way to measure global warming is through “temperature alignment” – a forward-looking benchmark that compares the level of emissions today against the potential for reducing them by a certain date in the future. The measure can be applied to a specific business, government, or investment portfolio.
For investors, global greening provides an opportunity to invest in companies positioning for a future net zero economy. After all, it’s important to recognize that climate risk represents substantial investment risk. Companies that prepare for the transition to sustainable energy sources will be able to deliver long-term returns, while those that do not could become obsolete.
If Net Zero is your path consider the following steps to align your investment allocation with the goals of a net zero economy. For example:
Reduce your exposure to high-carbon emitters and companies not making forward-looking commitments to transform to the net zero economy.
Prioritize investment decisions based on companies actively reducing reliance on fossil fuels and meeting science-based targets.
Target specific sustainable sectors (e.g., clean energy, green bonds) based on your asset allocation strategy – and diversify investments among those holdings.
Monitor ongoing research and available data to measure temperature alignment to ensure your issuers and investments are meeting published transition plans. This benchmark should be reviewed with the same rigor as traditional financial data.
The United States and the entire world have a choice to reduce the global. However, the effort also offers an opportunity to invest in climate innovation. The future will bring the survival of the fittest, is your portfolio ready.
What is a Net Zero Economy?
September 1, 2021 · Blog, Financial Planning, News
⏱ 3 min read
President Biden re-entered the United States in the Paris Agreement. This is an international treaty first signed in 2015 in which countries around the globe committed to mitigating climate change. Specifically, the goal of the Paris Accord is to limit global warming to no more than 1.5 degrees Celsius above pre-industrial levels.
This objective would generate what is called a net zero global economy, which means creating a balance between the amount of greenhouse gases produced and the amount of greenhouse gasses removed from the atmosphere. The main engine that places carbon back into the soil is healthy vegetation that grows all years round, these are called cover crops and reforestation. You can help by using the Ecosia search engine.
The initial benchmark is to achieve net zero carbon dioxide emissions by 2050 and net zero emissions of all greenhouse gases by 2070. However, accomplishing these lofty goals will require a remarkable transformation of the global economy and global farming practices.
A way to measure global warming is through “temperature alignment” – a forward-looking benchmark that compares the level of emissions today against the potential for reducing them by a certain date in the future. The measure can be applied to a specific business, government, or investment portfolio.
For investors, global greening provides an opportunity to invest in companies positioning for a future net zero economy. After all, it’s important to recognize that climate risk represents substantial investment risk. Companies that prepare for the transition to sustainable energy sources will be able to deliver long-term returns, while those that do not could become obsolete.
If Net Zero is your path consider the following steps to align your investment allocation with the goals of a net zero economy. For example:
Reduce your exposure to high-carbon emitters and companies not making forward-looking commitments to transform to the net zero economy.
Prioritize investment decisions based on companies actively reducing reliance on fossil fuels and meeting science-based targets.
Target specific sustainable sectors (e.g., clean energy, green bonds) based on your asset allocation strategy – and diversify investments among those holdings.
Monitor ongoing research and available data to measure temperature alignment to ensure your issuers and investments are meeting published transition plans. This benchmark should be reviewed with the same rigor as traditional financial data.
The United States and the entire world have a choice to reduce the global. However, the effort also offers an opportunity to invest in climate innovation. The future will bring the survival of the fittest, is your portfolio ready.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.

 Did you know that homeowner’s insurance doesn’t cover flood damage? Because of this, homes located in a Special Flood Hazard Area (SFHA) are required by lenders to purchase a separate flood insurance policy. However, there are millions of homes at risk that also experience periodic flooding but are not located in the most hazardous zones.



 Today, 70 percent of college students graduate with an average of $30,000 in student loan debt. The average payment is nearly $400 a month and will take about 20 years to pay off. On an individual level, paying off high debt can delay hopes of saving to buy a house, start a family, launch a business or invest for retirement.